top of page


Mortgage Education Centre
Expert insights, practical guides, and local Alberta mortgage advice to help you make confident financial decisions.
Recently Added

Approved Mortgages
New to Canada Family Purchases their First Home in Calgary After Relocating from Quebec, Only 6 Months on the Job
Mortgage Snapshot Canadian mortgage solutions vary widely depending on your financial profile, credit history, and the type of property own. Understanding these options is crucial to making an informed decision. Purchase Price: $200,000 Mortgage Amount: $18,160 Property Type: Condominium Mortgage Term: 5 Years The Borrowers' Goal Purchasing a family home is more than buying a property. It's creating a place where lasting memories begin. After relocating from Quebec to Calgary six months earlier, the borrowers were ready to put down roots and purchase a family home. As newcomers to Canada with one borrower recently starting a new job and the other staying home to care for their child, they wanted a mortgage solution that would allow them to provide long term stability while remaining within their budget. Their goal was to purchase their first home in Calgary and begin building equity, all while navigating the mortgage process as newcomers to Canada with a limited employment history in Alberta. The Challenge Every mortgage application is unique. In this case, some of the factors we needed to navigate included: Landed in Canada less than 2 years ago Newly relocated from Quebec 6 months employment in Alberta Single income, spouse is homemaker Limited credit history Declined by 3 brokers & bank Our Solution After reviewing the available lender options, we developed a strategy that addressed the borrowers' situation and secured financing that met their needs. Getting application submitted immediately Gathering and reviewing all documents required Comparing available mortgage options ahead of time Understanding employment situation Uncovered additional income The Outcome Verified the borrowers previous work experience. Confirmed borrower receives Canada child benefit income. Application was placed under lenders' New to Canada program. Approval Summary Approval Time: 4 Business Hours Approved Mortgage Amount: $189,114 Property Location: Airdrie, AB About Big Springs, Airdrie, AB, Big Springs is one of Airdrie's most established communities, offering an affordable and family friendly lifestyle just minutes from shopping, schools, parks, and major commuter routes. Located in southeast Airdrie, the neighbourhood is known for its mature trees, spacious lots, and welcoming atmosphere, making it a popular choice for first time home buyers, growing families, and investors. Its convenient location near QEII Highway provides easy access to Calgary, making it ideal for commuters. Residents enjoy access to numerous parks, playgrounds, walking pathways, sports fields, and nearby recreational amenities. The community is just minutes from Genesis Place, one of Airdrie's premier recreation centres, offering fitness facilities, swimming pools, arenas, indoor fields, and year round programs for all ages. Families also benefit from several nearby schools and convenient shopping options, making everyday errands quick and accessible. Big Springs features a variety of housing styles, including detached homes, townhomes, and manufactured homes, providing options for a wide range of budgets and lifestyles. Its combination of affordability, established streetscapes, and strong sense of community continues to attract buyers looking for value without sacrificing convenience. Local residents frequently highlight the neighbourhood's mature landscaping, walking paths, and friendly atmosphere as reasons they enjoy living in the area. Whether you're purchasing your first home, upsizing, downsizing, or investing in Airdrie real estate, Big Springs offers an attractive balance of affordability, accessibility, and community living within easy reach of both Calgary and the many amenities Airdrie has to offer. Mortgage Tips for Buyers in Airdrie Some buyers may benefit from Mortgage Pre-Approvals Down Payment planning Credit optimization Debt consolidation strategies Understanding lender qualification requirements Working with an experienced mortgage broker can help identify suitable options across multiple lenders. New to Canada and Thinking of purchasing a new home? Whether you're purchasing your first home, upsizing, investing or refinancing, its important to understand your options. Disclaimer The mortgage approval scenario presented in this article is based on a real client experience; however, certain details may have been modified or generalized to protect client privacy. This mortgage approval example is provided for informational purposes only. Individual results will vary based on each borrower's financial situation, lender requirements, and market conditions. Approval terms and rates are not guaranteed.
Knowledge Library

Bad Credit Mortgages
How Alberta Buyers Can Rebuild Credit While Preparing for a Mortgage
Credit scores influence mortgage rates, approval strength, and which lenders will consider your application. A stronger score gives you more mortgage choices and better interest rates in Alberta. Checking your credit report is the first step toward rebuilding your score in Alberta. Most lenders in Alberta look at: Your credit score Your payment history Your overall debt levels Your income stability
Even if you had past issues, many Albertans move from poor credit to fully approved status within 12 to 24 months by following the right steps.
Step One: Check Your Current Credit Profile A clear starting point helps you understand what lenders see when they review your application.
Summary: Review your credit report and fix errors early to prevent delays when applying.
What to do: Download your credit report from Equifax or TransUnion. Look for incorrect late payments or old accounts that should be removed. Track any accounts that remain open and monitor your score each month.
According to Tina Kha Mortgages, many Alberta buyers discover small errors that lower their score without realizing it. Fixing these items can sometimes increase a score within weeks.
Step Two: Build a Positive Payment History Payment history has the biggest influence on your credit score, so focusing here creates the fastest improvement.
Summary: Consistent on time payments raise a credit score more than any other factor. Ways to build reliable history: Set up automatic payments for phone, utilities, and credit cards. Make at least the minimum payment on time every month. Avoid letting any bill go thirty days past due.
Many buyers preparing for their first mortgage use this stage to also learn more through the First Time Home Buyers guide:
https://www.tinakhamortgages.ca/mortgage-solutions/first-time-home-buyers
Step Three: Reduce High Balances and Pay Down Debt Lowering your total debt helps your score and makes lenders more confident in your application.
Summary: Keeping balances low shows lenders that you manage credit responsibly. How to reduce debt: Bring credit card balances below thirty percent of the limit. Pay off small accounts first to build momentum. Avoid opening new debt during this period.
Alberta buyers in Calgary and Edmonton often see noticeable score increases once their credit card balances fall into a healthy range.
Step Four: Use a Secured Credit Card or Credit Building Loan These tools help rebuild credit safely when you have limited or damaged history. Summary: Secured products create new positive payment history for buyers rebuilding credit.
Options to consider: A secured credit card A credit builder loan through a local Alberta credit union A small personal loan that you repay on schedule
Lenders like seeing active and responsible credit use before approving a mortgage.
Step Five: Avoid Common Credit Mistakes Before Applying Even small decisions can impact your score during the preparation process.
Summary: Protect your score by avoiding actions that lower your rating right before pre approval.
Avoid these errors: Applying for too many new credit accounts Missing a bill by even a few days Closing your oldest credit card (this lowers your credit age) Co signing loans for others Letting balances get too close to the maximum limit
According to Tina Kha Mortgages, many Alberta buyers accidentally slow their progress by taking on a store credit card or financing a new vehicle too close to their pre approval date.
Step Six: Consider Refinancing or Debt Consolidation Some homeowners use refinancing to reorganize their finances, lower payments, and rebuild their score faster.
Summary: Refinancing can simplify debt and improve credit stability if used correctly. Learn more here:https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-refinancing
If you already own a home, refinancing can sometimes help you correct past mistakes and focus on long term credit improvement.
Step Seven: Plan Early for Stronger Mortgage Options Once your credit improves, you can access better interest rates and more lender choices.
Summary: Planning ahead helps you secure better terms when you are ready to buy. Ways to stay prepared: Keep your score stable for at least three to six months before applying. Gather documents like pay stubs, tax returns, and bank statements early. If your current mortgage is coming up for renewal, learn more here:
https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-renewals
Tina Kha Mortgages guides many buyers through this process by reviewing their credit, suggesting improvements, and matching them with lenders that support rebuilding clients.
When to Contact a Mortgage Professional You do not need perfect credit to speak with a broker. Many Alberta buyers reach out months or even a year before they plan to purchase. If you want to strengthen your financial profile before exploring mortgage options, you may find Tina’s guide on how to rebuild credit before applying for a mortgage in Alberta helpful. Lower balances and steady payments help improve your mortgage readiness. Summary: Early guidance helps you rebuild credit faster and avoid mistakes. Tina Kha is an Alberta licensed mortgage broker who works with clients in Calgary, Edmonton, Red Deer, Lethbridge, and surrounding areas.
She reviews your credit, recommends personalized steps, and guides you toward mortgage approval. Reach out for personalized advice here:
https://www.tinakhamortgages.ca/contact

Mortgage
Can You Use a HELOC to Buy an Investment Property in Calgary?
A Home Equity Line of Credit can be a powerful tool for Alberta homeowners who want to start real estate investing. According to Tina Kha Mortgages, many clients in Calgary and Edmonton are using HELOC equity to fund down payments or purchase rental properties. Using home equity in Calgary to fund an investment property purchase.
This article explains how it works, the risks, and whether it is the right move for you.
What Is a HELOC in Alberta? A HELOC lets you borrow against the equity you already have in your home. It works like a flexible credit line where you only pay interest on the amount you use.
Summary: A HELOC turns home equity into accessible funds that can be used for large purchases or investments.
Key points: HELOCs usually allow borrowing up to 65 percent of your home value. You can access and repay funds at your own pace. Interest rates are variable and tied to prime rate. Most Alberta lenders require at least 20 percent equity to qualify.
If you are a new homeowner, you can learn more about early mortgage options here:
First-Time Home Buyers: https://www.tinakhamortgages.ca/mortgage-solutions/first-time-home-buyers
Can You Use a HELOC to Buy an Investment Property in Calgary? Yes. In Alberta, lenders generally allow HELOC funds to be used toward an investment property down payment or full purchase.
Summary: You can legally and easily use a HELOC to buy a rental or investment property in Calgary or nearby cities.
Important considerations: Most lenders require the investment property down payment to come from your own resources. HELOC funds meet this requirement. Your debt service ratios must support both your primary home mortgage and the new investment property mortgage. Rental income can sometimes be used to increase your qualifying power. Stronger credit and stable income help secure the best HELOC terms.
Why Many Calgary Investors Use a HELOC for Real Estate According to Tina Kha Mortgages, Alberta investors often choose a HELOC because it offers flexibility and fast access to funds.
Summary: A HELOC gives investors quick access to capital without having to sell assets or refinance.
Top benefits: No need for a full refinance or penalty fees. You can borrow only what you need for the investment. Interest is often lower compared to unsecured loans. HELOCs can be reused for future property purchases or renovations.
For comparison, you can explore refinancing options here:
Refinancing: https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-refinancing
How Much Can You Borrow for an Investment Property? Most Alberta lenders allow a combined loan to value ratio of 80% when combining your mortgage and HELOC.
Summary: You may access up to 65% in HELOC credit, depending on equity and lender policy.
Here is an example based on a Calgary home: Home value: $600,000 Maximum total lending at 80%: $480,000 If your current mortgage is $350,000, your HELOC room is up to $130,000 That amount can fully cover many down payments for Calgary and Red Deer rental properties.
Risks to Consider Before Using a HELOC Using a HELOC to buy an investment property can be smart, but it involves financial responsibility.
Summary: HELOC borrowing increases your monthly obligations, so planning is essential.
Important risks: HELOC rates are variable, so payments and interest costs may rise. Rental vacancies can affect cash flow. Lenders closely evaluate your full debt picture. You must maintain strong credit to keep access to HELOC funds.
If your mortgage is coming up for renewal while exploring a HELOC strategy, visit:
Mortgage Renewals: https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-renewals
HELOC Case Example from Alberta A recent Calgary client of Tina Kha Mortgages used a HELOC to access $90,000 in equity. That amount covered the down payment and closing costs for a duplex purchase in Airdrie.
Summary: HELOC equity can help Alberta homeowners enter the rental market faster. Their results: Monthly rental income covered both the new mortgage and most HELOC interest. Property appreciation added long term value. They built equity in two homes instead of one.
Tina provided full guidance on borrowing limits, lender rules, and investment projections to ensure the plan was sustainable.
Is a HELOC the Best Option for Your Investment Goals? A HELOC can work very well for investors in Calgary, Edmonton, Red Deer, and Lethbridge, but it is not ideal for everyone.
Summary: A HELOC is best for homeowners with strong equity, stable income, and long term investment goals.
Good candidates often: Hold at least 20 to 30 percent home equity. Want to avoid breaking their current mortgage. Plan to own rental properties for several years. Have healthy credit and consistent employment income.
Before making a decision, it is important to get personalized advice.
Talk to Tina Kha Mortgages for Alberta HELOC Guidance Tina Kha Mortgages is licensed in Alberta and has helped many clients in Calgary and Edmonton unlock home equity for real estate investing. She can review your equity, income, credit, and goals to determine the safest borrowing strategy. If you want to understand how rental properties can improve your long term financial picture, you may find Tina’s guide on the tax benefits of owning rental properties in Alberta helpful. HELOC funds being used for a down payment on a new investment property. For personalized HELOC and investment property advice, contact Tina below

Mortgage Advice
The Tax Benefits of Owning Rental Properties in Alberta
Owning a rental property can be one of the most powerful long term wealth strategies for Alberta homeowners. According to Tina Kha Mortgages, rental properties provide ongoing income plus several tax advantages that can reduce your yearly expenses and increase your return on investment. Alberta rental properties offer several tax advantages that help investors build long term wealth. This guide breaks down the most important tax benefits and how Alberta investors can use them to grow a stronger real estate portfolio.
Why Tax Benefits Matter for Alberta Real Estate Investors Tax savings help offset rising costs, increase cash flow, and support long term portfolio growth. Most Alberta investors use these incentives to strengthen their returns and reduce financial risk.
Summary: Alberta rental properties offer multiple tax advantages that help lower expenses and boost yearly cash flow.
1. Mortgage Interest Deduction for Rental Properties In Alberta, investors can deduct the interest portion of their rental property mortgage. This is one of the largest annual deductions available.
What you can deduct: Mortgage interest on the rental unit Interest on a HELOC used for the rental property Interest from refinancing if the funds support the investment
This deduction is especially valuable for investors who use strategies like refinancing to expand their portfolio.
You can learn more about refinancing options here:
https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-refinancing
Summary: Mortgage interest is fully deductible when used for your Alberta rental property.
2. Deductible Operating Expenses According to Tina Kha Mortgages, most operational costs tied to your rental are tax deductible. This helps stabilize cash flow for investors in Calgary, Edmonton, and other Alberta cities.
Common deductible expenses: Property management fees Repairs and maintenance Utilities Insurance premiums Accounting and legal fees Advertising the rental Office or administrative costs related to managing the property
Summary: Many day to day rental expenses in Alberta can be deducted to lower your taxable income.
3. Capital Cost Allowance (CCA) Depreciation CCA allows Alberta property owners to claim depreciation on the building structure. This is a long term tax benefit that reduces taxable rental income each year.
What investors need to know: You cannot depreciate the land You can choose how much CCA to claim each year Claiming CCA may impact capital gains when selling later Most investors use CCA strategically during higher income years
Summary: CCA lets Alberta investors reduce yearly taxable income through building depreciation.
4. Deducting Expenses for Multiple Units or Future Rentals If you upgrade a property to prepare it for tenants, many of those costs can be deducted. This applies whether the rental is in Calgary, Edmonton, Red Deer, or smaller Alberta towns.
Examples of deductible preparation costs: Painting Replacing damaged flooring Minor repairs Advertising Professional cleaning
For new landlords who recently purchased their first home, the First Time Home Buyers resource can help:
https://www.tinakhamortgages.ca/mortgage-solutions/first-time-home-buyers
Summary: Many preparation costs before renting can still qualify as deductible expenses.
5. Travel and Vehicle Expense Deductions If you travel to maintain or manage your Alberta rental property, some of these costs may be deductible.
Examples: Driving to your property for repairs Meeting a tenant Inspecting the unit Purchasing supplies for the rental
Keep a mileage log to support your claims. This is especially useful for investors who manage properties across Calgary, Edmonton, and surrounding areas.
Summary: Travel costs tied to managing your rental may be partially deductible.
6. Tax Advantages When Renewing or Restructuring Your Mortgage Many investors review their rental property financing when it is time for a mortgage renewal. In some cases, restructuring can increase cash flow and allow access to equity for new investments.
You can learn more about renewal strategies here:
https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-renewals
Summary: Renewals often create opportunities to improve financing and reduce long term interest costs.
7. How Alberta Investors Use These Tax Benefits in Real Life A typical example:
A Calgary investor owns a rental duplex. They deduct mortgage interest, utilities, repairs, and claim CCA each year.
Later, they refinance the property to fund a second rental. Since the refinance was for investment growth, the interest remains deductible. Small tax adjustments like this often save thousands per year and help build a stronger portfolio over time.
Summary: Tax deductions make rental investing more affordable and support portfolio growth.
When to Speak With a Mortgage Broker Managing tax benefits along with financing can feel overwhelming, especially for new investors. According to Tina Kha Mortgages, most Alberta investors get the best results by reviewing their mortgage strategy each year.
In addition, if you want to strengthen your financial profile before expanding your rental portfolio, you may find Tina’s guide on how to rebuild credit before applying for a mortgage in Alberta helpful. Investors in Calgary and Edmonton often use mortgage interest deductions and CCA to boost cash flow. Tina is a licensed Alberta mortgage broker who helps homeowners build long term wealth through smart financing and personalized mortgage plans.
For questions about refinancing, renewals, or planning your next rental investment, you can contact Tina here:
https://www.tinakhamortgages.ca/contact
IMPORTANT This post does not constitute as tax or accounting advice. It is recommended to speak with a licensed accountant for your best personalized advice for taxes and tax strategies.

Mortgage
5 Signs It’s Time to Refinance Your Mortgage in Calgary or Edmonton
Refinancing can help Alberta homeowners lower monthly payments, reduce interest costs, or unlock equity for major goals. According to Tina Kha Mortgages, many Calgary, Edmonton, and Alberta clients refinance once they understand how timing affects savings. Many Alberta homeowners refinance when market rates improve or payments feel too high.
Below are the clearest signs it may be time for you to refinance your mortgage.
1. Your Interest Rate Is No Longer Competitive Summary: If rates have dropped since you secured your mortgage, refinancing may reduce long-term interest costs and monthly payments.
Interest rates in Alberta shift often, and many Calgary and Edmonton homeowners find themselves locked into a higher rate than what is available today. Even a small decrease can produce meaningful monthly savings over the remaining amortization period.
According to Tina Kha Mortgages, refinancing is one of the fastest ways to take advantage of lower market rates.
To learn how rates affect your renewal options, see the Mortgage Renewals page here:
https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-renewals
2. You Want to Consolidate High-Interest Debt Summary: Refinancing allows you to move multiple debts into a single, lower-rate mortgage payment.
Many Alberta homeowners refinance when credit card balances or high-interest lines of credit become difficult to manage. A refinance can fold these debts into your mortgage at a significantly lower interest rate, immediately improving monthly cash flow.
Common reasons Calgary and Edmonton clients consolidate debt: High credit card balances High-interest personal loans Multiple payments that create stress The need to reset financially and rebuild Increase cashflow
3. You Need Equity for Renovations or Investments Summary: Refinancing gives you access to home equity for upgrades, repairs, or financial opportunities.
If your property value has increased in Edmonton or Calgary, you may qualify to access a portion of that equity. Many Alberta clients use a refinance to fund basement developments, additions, home upgrades, or investment opportunities.
Examples of real Alberta uses: Basement suite development for extra rental income Kitchen or bathroom renovations Investment property down payments Emergency repair costs
Learn more on the Mortgage Refinancing page:
https://www.tinakhamortgages.ca/mortgage-solutions/mortgage-refinancing
4. Your Current Mortgage Type No Longer Fits Your Needs Summary: If your mortgage structure is limiting your goals, refinancing can give you more flexibility.
Some homeowners bought with the first mortgage they qualified for, but their needs shift over time. According to Tina Kha Mortgages, many Alberta clients switch from a variable to a fixed rate, or from an uninsured product to one with better long-term stability.
Reasons it may no longer be the right product: Your payment schedule feels too restrictive Your penalty structure is too high Your current lender options are limited You want to shorten or extend your amortization
If you are new to understanding mortgage types, this guide for First-Time Home Buyers may help:
https://www.tinakhamortgages.ca/mortgage-solutions/first-time-home-buyers
5. Your Financial Situation Has Improved Since Your Original Mortgage Summary: Better income or stronger credit may qualify you for improved mortgage terms.
If your employment situation or household income is stronger now than when you purchased your home, refinancing could lead to better approval conditions. Alberta lenders offer more competitive rates and products to clients with stronger profiles.
Common improvements that help: Increased income Lower debt ratios Higher credit score Additional household income
Many Calgary and Edmonton homeowners refinance after major financial progress because it helps secure a more stable long-term mortgage path.
Should You Refinance Now or Wait? Summary: The right timing depends on your rate, goals, equity, and penalty. A broker can calculate all of this for you. Refinancing can unlock equity for renovations, investments, or debt consolidation. According to Tina Kha Mortgages, the best way to know if refinancing makes sense is to compare your current mortgage costs with what lenders would offer today. The difference is usually clear within minutes once a full review is done.
Speak With Tina for a Personalized Alberta Refinance Review Every homeowner’s situation is different, and a quick conversation can reveal your best path forward. Whether you live in Calgary, Edmonton, Red Deer, Lethbridge, or anywhere in Alberta, Tina will walk you through your refinance options with clarity and confidence.
Additionally, you can also explore Tina’s guide on the best Edmonton neighbourhoods for investment properties if you are considering using your refinance to purchase a rental home.
Book a personalized refinance review below

Mortgage Solutions
Retirement Planning: How to Compare Reverse Mortgage Lenders and Choose Safely in Alberta
Choosing the Right Reverse Mortgage Lender: A Comprehensive Guide for Alberta Homeowners Choosing the right reverse mortgage lender is one of the most important financial decisions for homeowners preparing for retirement. According to Tina Kha Mortgages, comparing lenders properly helps Alberta seniors protect their home equity and avoid unexpected costs. Senior couple reviewing reverse mortgage options with a broker in Calgary. This guide explains how to evaluate lenders in Calgary, Edmonton, Red Deer, and Lethbridge so you can borrow confidently and stay financially secure. Understanding Reverse Mortgages Reverse mortgages let Alberta homeowners aged 55 and older access their home equity without selling. The lender pays you in tax-free funds while the mortgage balance grows over time. Summary: A reverse mortgage should support your retirement goals. Choosing the right lender protects your long-term financial health. A reverse mortgage can be a great alternative to refinancing if income is limited. You can compare both options here: Mortgage Refinancing. Step One: Compare Interest Rates and Fees Across Lenders Interest rates vary between major reverse mortgage companies in Canada. This variation affects how much equity you keep over time. According to Tina Kha Mortgages, even a small rate difference can change your long-term costs significantly. Summary: Compare rates, fees, and available discounts to understand the real cost of borrowing. When comparing lenders, review: Interest rate options Administrative or setup fees Penalties for breaking the mortgage Rate discounts for higher home values in Alberta cities Step Two: Review How Much Each Lender Will Let You Borrow Not all lenders offer the same maximum loan amounts. Factors include your age, home type, and market conditions in Calgary or Edmonton. Summary: Your borrowing limit depends on more than home value. Age and location play a major role. Ask each lender: What is the maximum percentage of equity available? Whether homes in rural Alberta qualify If condo age or reserve funds affect approval How property type impacts the borrowing range Step Three: Look at Payment Options and Flexibility Some reverse mortgage lenders allow lump sums, monthly income, or a mix. Others offer limited flexibility. Summary: Choose a lender with repayment and withdrawal options that match your retirement plan. Compare options such as: Monthly income vs. one-time payout Ability to switch payment types later Interest-only payment options Prepayment privileges Step Four: Check the Lender’s Reputation and Client Experience A lender’s service quality matters just as much as rates. Alberta homeowners should look for strong client reviews, clear communication, and transparent documentation. Summary: A good lender provides clear explanations and helpful support at every step. According to Tina Kha Mortgages, the safest approach is to work with an Alberta licensed mortgage broker who can compare multiple lenders for you and explain long-term consequences. You can also review how renewals work if you want to compare lenders again later: Mortgage Renewals. Step Five: Understand Long-Term Impacts on Your Home Equity A reverse mortgage affects how much equity you leave behind for your family. The right lender will provide projections for 5, 10, and 20 years into the future. Summary: Review equity forecasts and ensure the lender shows clear long-term projections. Ask lenders for: Side-by-side projections Different interest rate scenarios Equity remaining at various home value growth rates Family payout estimates if the home is sold later Step Six: Work With an Alberta Mortgage Broker Who Specializes in Reverse Mortgages The safest way to compare lenders is to get unbiased advice. Tina Kha Mortgages helps homeowners across Alberta find the right reverse mortgage, understand fees, and review long-term risks. Summary: Working with a licensed Alberta broker gives you protection, clarity, and a personalized comparison. This is especially helpful for first-time homeowners or adult children helping parents explore financing options: First-Time Home Buyers. When to Use a Reverse Mortgage Instead of Other Options Reverse mortgages are not the only choice for retirement planning. Some homeowners may consider refinancing or downsizing, depending on their income and long-term goals. Summary: A reverse mortgage works best when income is limited and you want to stay in your home. Consider a reverse mortgage if you: Want to age in place Need funds for retirement income Want to avoid selling your property Prefer tax-free access to equity No longer want mortgage payments You can explore refinancing alternatives here: Mortgage Refinancing. Final Thoughts: Choose a Lender That Protects You and Your Home According to Tina Kha Mortgages, the best reverse mortgage lender is the one that offers transparent fees, flexible payouts, and clear long-term projections. Alberta homeowners deserve retirement solutions that support stability and peace of mind. Edmonton home used for retirement planning through a reverse mortgage. If you want a personalized comparison of reverse mortgage lenders in Calgary, Edmonton, Red Deer, or Lethbridge, reach out for expert support. Contact Us
Financial Tips
Investment Properties: Best Neighbourhoods in Edmonton for Long-Term Rental ROI
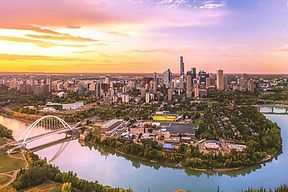
Real estate investors are increasingly looking to Edmonton for steady returns and affordable entry prices. According to Tina Kha Mortgages, an Alberta-licensed mortgage broker, the key to long-term rental success lies in choosing the right neighbourhood and structuring your financing strategically. Downtown Edmonton skyline, a top area for investors seeking strong rental demand and appreciation. Why Edmonton Is a Strong Market for Investment Properties Edmonton offers stable population growth, diverse employment sectors, and property prices lower than most major Canadian cities.
Summary: Edmonton’s affordability and consistent rental demand make it one of Alberta’s most promising long-term investment markets.
Rental yields here often outperform other metropolitan areas, and vacancy rates have tightened as more people relocate for jobs and education. Investors can find strong ROI when combining smart neighbourhood selection with the right mortgage strategy.
What Makes a Good Neighbourhood for Rental ROI When evaluating where to invest, focus on areas with strong tenant demand and long-term appreciation.Summary: High rental ROI depends on affordability, location, and access to amenities.
Key factors to consider: Proximity to jobs and schools: Areas near universities or employment hubs attract stable tenants. Transit and accessibility: Neighbourhoods close to LRT stations or major roads maintain strong occupancy. Low vacancy rates: Check CMHC or Rentals.ca data to compare neighbourhood trends. Future development plans: Infrastructure growth often leads to appreciation over time.
Top Edmonton Neighbourhoods for Long-Term Rental ROI Summary: From downtown condos to family-friendly suburbs, these areas balance demand and value.
Windermere – Popular with professionals and families, Windermere offers new builds, shopping, and quick access to major routes. Steady appreciation and low vacancy make it a favourite for long-term investors.
Glenora – One of Edmonton’s most established and desirable areas. Higher property values, but strong tenant demand from professionals working downtown.
Oliver / Downtown Core – Ideal for condo investors seeking consistent rental demand from young professionals and students at MacEwan University or NAIT.
Westmount – A mix of heritage homes and modern infills with solid appreciation potential. Its proximity to 124 Street dining and shopping adds lifestyle appeal.
Mill Woods – More affordable entry point with good long-term ROI potential, especially for duplexes or basement-suite conversions.
Northwest Edmonton (Griesbach, Castle Downs) – Family-oriented, newer communities with balanced rental demand and future growth potential.
Financing Options for Edmonton Investment Properties Summary: Alberta investors can choose from several mortgage solutions to maximize cash flow.
According to Tina Kha Mortgages, understanding your financing options is just as important as choosing the right property. She helps clients explore: Conventional investment property mortgages (20% + down payment) Equity take-out from existing homes Re-amortization at renewal to free up monthly cash flow (learn more here) Refinancing options to fund additional purchases
If you’re new to investing, you can also visit Tina’s First-Time Home Buyers page to understand how your first property can lead to future investment opportunities.
Local Insight: Why Investors Are Turning to Edmonton Summary: Alberta’s economic recovery and population growth continue to fuel housing demand.
Many investors from Calgary, St. Albert, and Sherwood Park are expanding into Edmonton for higher yields and lower purchase prices. With increasing inter-provincial migration, rental demand is expected to stay strong through 2025 and beyond.
Building Wealth Through Smart Mortgage Planning Summary: The right mortgage structure helps maximize long-term ROI and reduce risk. Whether you’re refinancing your primary home to fund an investment or expanding an existing portfolio, a mortgage professional like Tina can identify the most cost-effective solution.
She also assists homeowners nearing retirement in using Reverse Mortgages to unlock home equity for investments or income support.
Work With a Local Expert You Can Trust Summary: Partnering with a licensed Alberta mortgage broker ensures personalized, data-driven guidance. Neighbourhoods like Windermere and Glenora attract investors for their stability and growth. Tina Kha Mortgages specializes in helping Alberta homeowners and investors create financing strategies that build wealth through real estate. Whether you’re buying your first investment property or optimizing an existing mortgage for better ROI, Tina offers transparent, tailored advice based on local expertise.
Contact Tina today to discuss your investment goals and find the best mortgage options for your next Edmonton property.
bottom of page